Not All Physician and Medical Provider Loans Are Built The Same
What Doctors (And Their Agents) Should Know...
If you’re a physician, resident, fellow, dentist, pharmacist, CRNA, or veterinarian, you may have heard:
“You can buy with zero down and no mortgage insurance.”
That’s true.
What’s not talked about enough is this:
Not all physician loans are structured the same.
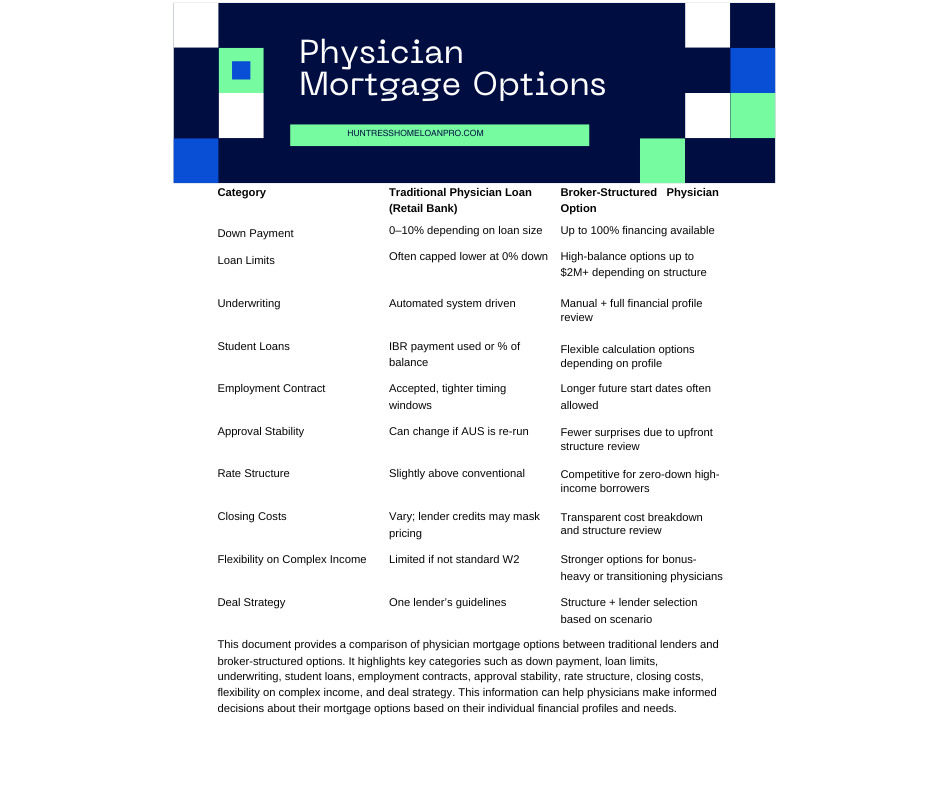
And at $1.5M–$2M purchase prices, structure matters more than headline marketing.
As a mortgage broker, I don’t have one physician loan.
We now have multiple physician-specific structures — and they are built very differently.
Let’s break that down.
The Myth: “A Doctor Loan Is a Doctor Loan”
Retail banks often offer:
- One physician product
- Automated underwriting
- Internal overlays
- Limited flexibility
- Strict DTI caps
- Tight projected income windows
That works — until it doesn’t.
Where deals start to wobble:
- Large student loan balances
- Start dates 4–5 months out
- High DTI due to zero-down jumbo pricing
- Contract bonuses or sign-on income
- Rapid career transitions
This is where structure becomes critical.
What Makes Broker Physician Structures Different?
As a broker, I can access:
✔ Manual Underwritten Physician Programs
A human underwriter reviews the full file — not just an algorithm.
That means:
- Compensating factors matter
- Asset strength matters
- Professional trajectory matters
- Context matters
On $1.8M purchases, that difference can save a deal.
✔ Higher Loan Limits at 100% Financing
Some of our physician programs allow:
- Up to $1.5M–$2M with zero down (credit dependent)
- No mortgage insurance
- Competitive DTI tolerances
Retail programs often taper down payment requirements as loan size increases.
✔ Student Loan Treatment That Makes or Breaks Approval
Depending on structure:
- Residency income can be used strategically
- Student loans may be excluded in specific residency scenarios
- Or calculated differently than conventional guidelines
On a $400,000 student loan balance, this can change qualifying power dramatically.
✔ Projected Income Flexibility
Some of our medical programs allow:
- Fully executed contracts
- Start dates up to 150 days out
- Standard employment contingencies only
Many retail banks tighten this window.
✔ Jumbo ARM Options That Are Assumable
Some physician ARMs:
- Are assumable
- Offer 5/6, 7/6, 10/6 structures
- Provide rate strategy flexibility
- Work well for short-term relocation or hospital track movement
Strategic, not emotional decisions.
Let’s Talk About Rates & Costs
Zero-down physician loans are specialty jumbo products.
That means:
- Rates are typically slightly higher than 20% down conventional loans
- Pricing reflects increased lender risk
- Closing costs vary based on structure and lender
What matters most isn’t the headline rate.
It’s:
- Total cost
- Stability of approval
- Underwriting confidence
- Whether the deal survives appraisal and final review
At $1.8M, volatility is expensive.
When Structure Matters Most
Broker physician programs shine when:
- High student loan debt
- 45–50% DTI scenarios
- Large zero-down jumbo loans
- Start date income scenarios
- Complex compensation structures
- Borrowers who need a manual review
A retail product may work beautifully for a clean $800K deal.
It may not hold at $1.8M.
The Real Advantage
I don’t sell “a doctor loan.”
I evaluate:
- Debt structure
- Contract timing
- Asset positioning
- Rate strategy
- Long-term mobility
- Risk of late-stage denial
And then I help you select the right structure.
That’s the difference between shopping and structuring.
You deserve guidance.
You deserve options.
And yes—you deserve a home, you've earned it. 💪🏡
Theresa Rolen – The Huntress Home Loan Pro
Mortgage Loan Originator
Phone:913-705-0049
Email:Theresa@SummitLendingUSA.com
NMLS #2249004 | Summit Lending NMLS #1850081 | Equal Housing Opportunity |https://nmlsconsumeraccess.org/
Book a 1:1 Strategy Call:
https://calendly.com/theresa-summitlending